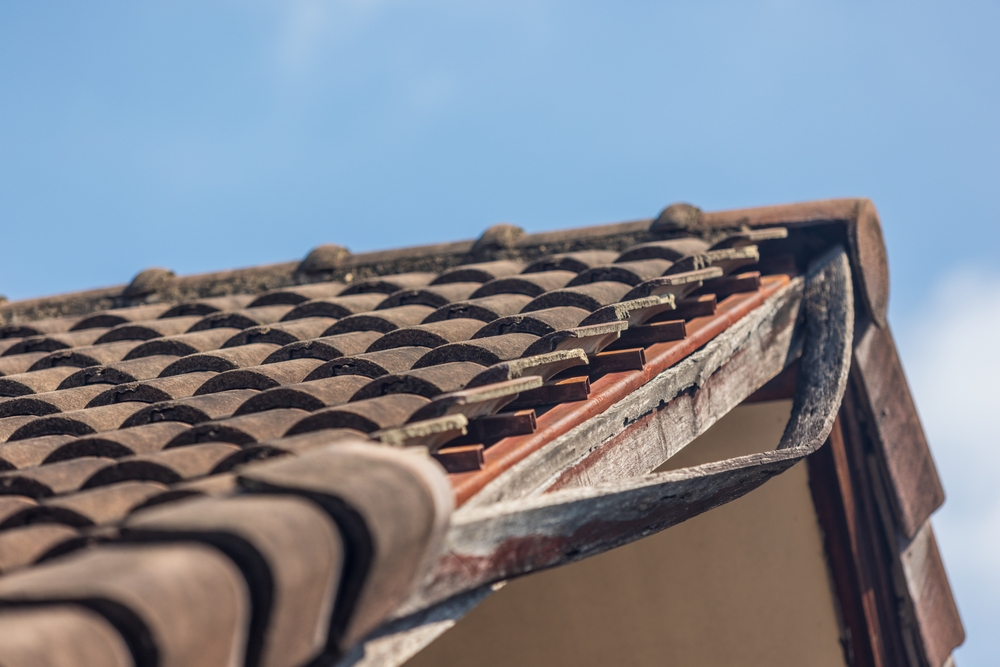
You remove part of a roof to carry out repairs.
The weather changes.
Water gets into the property and damages ceilings, walls, flooring or furniture.
It is exactly the sort of situation a roofing contractor hopes never happens, but if it does, one question quickly follows:
Will public liability insurance cover the water damage?
Potentially, but it is not something roofers should automatically assume.
Public liability insurance is designed to cover eligible claims from members of the public for injury or damage to their property arising from your business activities.
However, whether water damage caused during roofing work is covered will depend on what happened, the wording of your policy, any relevant exclusions or conditions and whether appropriate precautions were taken.
Can Public Liability Insurance Cover Water Damage?
Public liability insurance can cover eligible claims involving accidental damage to third-party property. The Association of British Insurers confirms that this can include the cost of compensation for loss of or damage to property.
For a roofer, water damage could arise in several ways.
You might:
- Accidentally damage part of an existing roof
- Leave an area temporarily exposed during work
- Fail to adequately weatherproof an opening
- Damage flashing or another roofing component
- Cause a leak that affects another part of the property
But the fact that water entered a property does not automatically mean a public liability insurer will pay the claim.
The cause matters.
So does the policy.
What If It Rains While a Roof Is Being Replaced?
This is one of the biggest risks roofing contractors need to consider.
Roof replacement often involves temporarily removing the protection that normally keeps a property watertight.
If rain arrives while part of the roof is exposed, water can spread quickly through a building.
The damage might affect:
- Ceilings
- Plaster
- Insulation
- Flooring
- Electrical systems
- Furniture
- Stock
- Equipment
That can turn a relatively modest roofing contract into a much larger potential claim.
Whether insurance responds will depend on the circumstances and policy terms.
An insurer may want to establish what protection was in place, what weather was expected and what caused the water ingress.
That is why weather protection should be treated as part of the job rather than something considered only once rain starts falling.
Can You Work on a Roof in the Rain?
There is a separate safety issue here too.
HSE guidance says workers should not consider going onto a roof in poor weather conditions such as rain, ice, frost or strong winds, particularly where conditions make the roof slippery.
Roof work is already high risk.
Wet surfaces can make it more dangerous.
If conditions deteriorate, the priority should be keeping people safe while also taking reasonable steps to protect the property.
Trying to rush work because rain has started can create an even bigger problem.
Does Weather Forecasting Matter?
From a practical risk-management perspective, yes.
Roofers cannot control the British weather, but they can plan around it.
Before opening up a roof, consider:
- Current weather conditions
- Forecast rainfall
- Wind
- How much of the roof can realistically be completed
- What temporary protection is available
- How the property will be secured before leaving site
HSE guidance stresses that roof work needs to be properly planned and that poor weather can make working at height unsafe.
Checking the forecast is therefore not simply about protecting the building.
It is also about protecting the people carrying out the work.
What If a Storm Causes the Damage?
This can make determining responsibility more complicated.
Imagine temporary protection is installed correctly but an unusually severe storm damages it overnight.
Whether you are legally liable for the resulting damage, and whether insurance responds, will depend on the facts.
The existence of water damage does not automatically mean the roofer was negligent.
Likewise, bad weather does not automatically remove responsibility.
The insurer may need to consider what precautions were reasonable in the circumstances and what the policy requires.
If there is any doubt, notify your insurer promptly.
What If a Subcontractor Leaves the Roof Exposed?
Subcontracting the work does not mean you should ignore the insurance implications.
Perhaps you are a main contractor and subcontract the roofing package.
Or you run a roofing business and bring in additional subcontractors when workload increases.
If water damage occurs, questions can arise over:
- Who actually carried out the work
- Who controlled the site
- Who installed temporary protection
- What your subcontract agreement says
- What insurance the subcontractor holds
- Whether your own policy covers your exposure
- Whether subcontracting arrangements were properly declared
Your insurer needs an accurate understanding of how you deliver your work.
If subcontractors form an important part of your roofing business, make sure your broker knows.
Don’t Wait Until It Rains to Read Your Policy
Roofing work and water damage are closely connected risks.
Removing a roof covering, even temporarily, can expose a property to potentially significant damage if the weather changes.
Public liability insurance can provide protection against eligible third-party property damage claims, but whether a particular water-damage incident is covered will always depend on the cause, circumstances and individual policy terms.
CHAS Insurance is an insurance broker that specialises in commercial insurance for construction businesses and trades, including roofing contractors.
We can discuss the type of roofing work you undertake, the buildings you work on, your use of employees and subcontractors and the risks your business faces.
Not sure whether your roofing insurance gives you the protection you need against water-damage claims? Contact CHAS Insurance today and speak to our team.
This article provides general information only and does not constitute insurance or legal advice. Policy cover, exclusions, conditions and claims decisions vary according to the insurer, wording and individual circumstances. Always check your own policy and speak to your insurer or insurance broker.